What is the market overview and industry significance of the Steel Products Market?
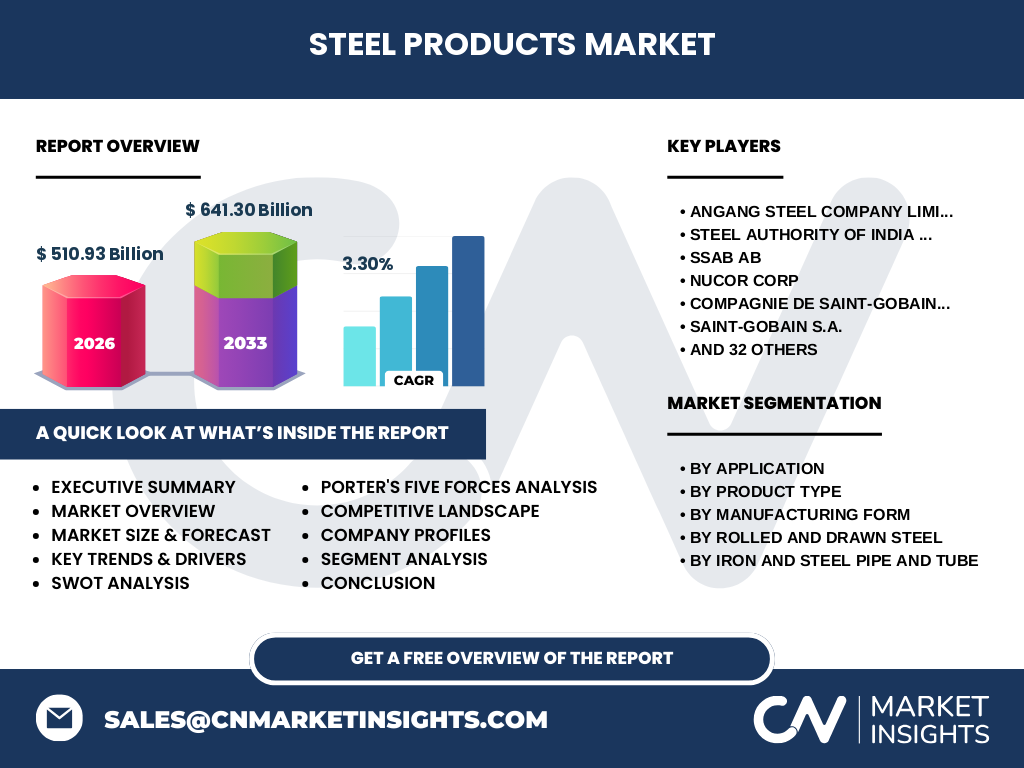
Our analysis indicates the Steel Products Market represents a foundational pillar of global industrialization, encompassing flat, long, and tubular steel items essential for infrastructure and manufacturing. Valued at 510.93 Billion in 2026, this sector dictates the economic momentum of heavy industries worldwide, driven by rigorous raw material inputs like coking coal and iron ore.
Key market drivers, restraints, challenges, and opportunities shaping the Steel Products Market
The Steel Products Market industry trends reveal that rapid urbanization acts as a primary growth catalyst, while stringent decarbonization mandates from bodies like the World Steel Association impose operational restraints. Logistical bottlenecks in raw material shipping create ongoing challenges. However, the transition toward lightweight automotive materials opens lucrative avenues for advanced high-strength steels.
Emerging trends and growth patterns in the Steel Products Market
The market is undergoing a profound structural shift toward green steel production utilizing hydrogen-based reduction methods. Industry pioneers such as SSAB AB are leading this transformation, significantly altering traditional manufacturing footprints and setting new benchmarks for sustainability across the value chain.
COVID-19 impact analysis and recovery trajectory
The pandemic caused unprecedented supply chain fractures and temporary facility shutdowns across major producing nations. However, post-crisis fiscal stimuli targeting public infrastructure accelerated a robust recovery, pushing the Steel Products Market past historical production baselines and realigning inventory models toward regional resilience.
Competitive Benchmarking
The competitive landscape is characterized by high market concentration among state-backed conglomerates and multinational giants like Nippon Steel Corporation, POSCO, and ArcelorMittal. Strategic dynamics hinge on operational consolidation, raw material vertical integration, and aggressive investments in low-carbon electric arc furnaces to capture tightening regulatory-compliant market share.
Executive Summary: High-Level Synthesis
Our comprehensive research confirms that the Steel Products Market market size is projected to reach 641.30 Billion by 2033, expanding at a steady CAGR of 3.30% from 2027. Stakeholders must pivot toward sustainable metallurgy and high-margin specialty tubular segments to navigate tightening environmental compliance and fluctuating input costs.
Market Forecast from 2027 to 2033
Driven by sustained demand in renewable energy infrastructure and urban renewal projects, the market will scale from its 2026 valuation to 641.30 Billion by 2033. This trajectory represents a steady 3.30% CAGR, reflecting stable long-term fundamentals despite macroeconomic headwinds and localized energy price volatility.
Segmentation Analysis of the Steel Products Market
Segmentation is categorized by application (Construction, Automotive, Energy, Packaging), product type (Flat Steel, Long Steel, Tubular Steel, Pipes, Tubes), and manufacturing form (Rolled and Drawn Steel, Iron and Steel Pipes). Construction dominates demand volume, while advanced Tubular Steel products capture higher margins in energy extraction sectors.
Regional Market Analysis and Geographic Distribution
Asia-Pacific commands the lion's share of consumption, anchored by massive construction output in China and India. Meanwhile, North America and Europe focus heavily on regulatory compliance, specialty alloy development, and high-value flat steel applications for premium automotive manufacturing.
In-Depth Regional Review
In Asia-Pacific, domestic overcapacity and stringent environmental caps drive structural consolidation among producers like Baosteel Group. Conversely, the North American market benefits from localized Steel Products Market analysis favoring electric arc furnace operators who capitalize on scrap metal availability and regional trade protections.
Strategic Company Profiles
Leading industry players such as Nucor Corp, Tata Steel, and JFE Steel Corporation employ distinct strategies. Nucor leverages flexible scrap-based mini-mills for cost efficiency, while Tata Steel emphasizes European green transformation initiatives and high-grade automotive flat steel portfolios.
Porter's Five Forces Analysis
Supplier power remains moderate-to-high due to consolidated iron ore mining cartels. Buyer power is tempered by the specialized nature of structural and tubular products. Threat of substitution is low in heavy construction, though aluminum and carbon composites pose growing threats in the automotive segment.
SWOT Analysis of the Sector
Strengths include unmatched material durability and recycling rates. Weaknesses stem from high carbon-emission profiles. Opportunities lie in green hydrogen steelmaking, while threats involve volatile coking coal prices and protectionist trade tariffs enacted by regional regulatory bodies.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with iron ore and coking coal extraction, progressing through blast furnace smelting or direct reduction. Intermediate processing yields rolled flat and long products before downstream fabrication serves end-users in automotive, construction, and energy pipelines.
Investment Insights and High-Potential Areas
Investors should target capital deployment toward low-emission electric arc furnace technologies and specialized alloy tubes for offshore energy applications. Companies demonstrating clear pathways to net-zero operations offer superior long-term risk-adjusted return profiles within the Steel Products Market.
Conclusion and Key Takeaways
The sector's steady march toward 641.30 Billion underscores its enduring industrial relevance. Success requires balancing traditional output volumes with aggressive decarbonization strategies, positioning forward-thinking enterprises to outperform macroeconomic volatility over the forecast period.
Research Methodology
Our baseline estimates are rigorously triangulated by combining official trade registry data, primary stakeholder interviews with c-suite executives across major producers like Voestalpine AG, and secondary macroeconomic indicators sourced from international trade and steel associations.
Scope of the Report
This report covers global production, consumption, trade flows, and pricing dynamics across flat, long, and tubular steel segments from 2026 to 2033. Geographic coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, excluding informal recycling sectors.
Recent Industry Developments
Recent strategic moves include major cross-border green hydrogen partnerships, capacity expansions by JSW Steel Limited, and facility modernizations by United States Steel Corporation aimed at reducing carbon intensity and complying with evolving environmental regulations.